What Does a Financial Plan Actually Include?
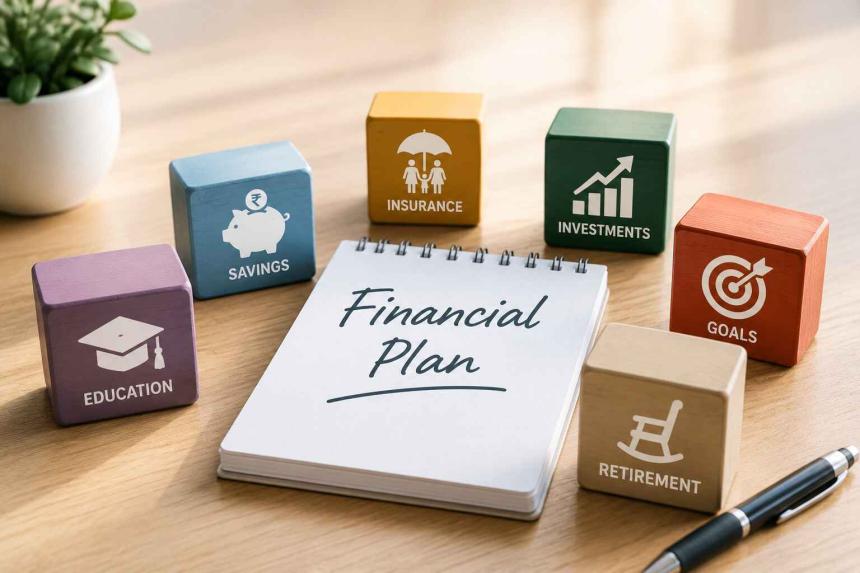
A useful financial plan brings several moving parts together: cash flow, goals, emergency savings, insurance, debt, investments, taxes, and retirement preparation. The real strength lies in how these pieces support one another.
A financial plan is not simply a list of investments, insurance policies, or tax-saving products. A useful plan connects your income, spending, savings, protection, investments, taxes, and future goals into one workable system. In other words, the real value of financial plan components comes from how they work together. Consider someone earning ₹80,000 a month. They may have a SIP, health insurance, and a savings account, yet still struggle when a job change, medical expense, marriage, or home purchase comes up. The problem may not be a lack of financial products. It may be the absence of a clear plan. That is where proper planning makes a difference. It gives every rupee a purpose while leaving enough room for unexpected changes.
Financial Plan Components Begin With Your Current Money PositionBefore deciding where to invest, a financial plan needs a clear picture of where you stand today. This is the starting point because recommendations without context can easily go wrong. Someone with a high income but large debt needs a different strategy from someone earning less but already having substantial savings. A proper financial snapshot generally looks at:
- Monthly income from salary, business, rent, or other sources
- Regular household and lifestyle expenses
- Existing loans and their interest rates
- Current bank balances and liquid savings
- Investments across mutual funds, shares, fixed deposits, PPF and other assets
- Insurance coverage already in place
- Tax liabilities and deductions
- Assets such as property, gold or other investments
- Financial commitments expected in the near future
The next step is to calculate your net worth. Simply put, this means subtracting what you owe from what you own. This exercise can reveal something important. A person may have several investments but still have a weak financial position because of expensive debt or insufficient liquid savings. So, financial planning does not begin with the question of which mutual fund to buy. It begins with understanding the financial picture as it actually exists.
Your Goals Decide Where the Money Should GoMoney becomes easier to manage when each major goal has a timeline and a financial target. Buying a house, funding a child's education, preparing for retirement, travelling, starting a business, or building wealth are not interchangeable goals. Each has a different time horizon and therefore needs a different approach. This is the heart of goal-based financial planning. Start by separating goals into three broad categories:
- Short-term goals that may arise within the next three years
- Medium-term goals that may need funding over three to seven years
- Long-term goals such as retirement or children's higher education
- Essential goals that cannot easily be postponed
- Lifestyle goals that can be adjusted when circumstances change
The amount required also needs attention. Saying "I want ₹50 lakh for my child's education" is only the beginning. You need to consider when the money will be required, what education may cost by then, and how much you need to invest today. Inflation matters here. A goal costing ₹20 lakh today will probably require considerably more several years from now. Once goals become measurable, investment decisions become more logical. Instead of investing because a product looks attractive, you invest because it has a role to play.
Cash Flow Shows Whether the Plan Can Actually WorkA financial plan may look excellent on paper and still fail if the monthly cash flow does not support it. This is why income and expenses deserve more attention than they usually receive. Take a household earning ₹1.2 lakh every month. If rent, EMIs, school fees, groceries, subscriptions, travel and discretionary spending consume ₹1.1 lakh, there is little room left for meaningful savings. Increasing the SIP amount alone will not solve the problem. A cash flow review should identify:
- Essential monthly expenses
- Flexible spending that can be reduced
- Existing EMIs and repayment schedules
- Regular investment commitments
- Annual expenses that need advance planning
- Irregular income such as bonuses
- Surplus available for savings and investments
It also helps to separate monthly expenses from annual expenses. Insurance premiums, school fees, vacations and major repairs can create sudden pressure when they are ignored during monthly budgeting. A strong plan therefore does not simply say "save more". It shows where the money can realistically come from. That makes the strategy easier to follow and much less likely to collapse after a few months.
Emergency Fund Planning Protects the Rest of the StrategyAn emergency can disrupt even a carefully designed investment plan. A sudden job loss, medical expense, urgent family responsibility or major repair can force you to withdraw investments at the wrong time. That is why emergency fund planning deserves a separate place in a financial strategy. The purpose of an emergency fund is not to generate high returns. Its purpose is accessibility and stability. A practical approach is to estimate essential monthly expenses and build a reserve based on your employment stability, dependants, income pattern and existing insurance. For example, a salaried employee with stable income may have a different requirement from a business owner whose monthly earnings fluctuate. Keep emergency money in relatively safe and accessible avenues rather than chasing returns with it. The key rules are simple:
- Calculate the reserve using essential expenses, not lifestyle spending
- Keep the money easily accessible
- Do not treat it as a fund for holidays or shopping
- Refill it after using it
- Review the amount when income or family responsibilities change
- Keep insurance separate from the emergency corpus
Most importantly, an emergency fund gives long-term investments breathing room. When an unexpected bill arrives, you do not necessarily have to sell an investment created for a goal five or ten years away.
Insurance Is About Protecting the Plan, Not Buying PoliciesInvestments can build wealth, but they cannot replace protection against major financial shocks. Imagine a family where one person earns most of the household income. If that income disappears because of premature death or a serious health event, the family's financial goals may immediately come under pressure. That is why insurance should be viewed as part of the financial structure rather than as an isolated product purchase. The planning process should consider:
- Health insurance requirements
- Life insurance needs
- Existing employer-provided coverage
- Dependants and their future financial needs
- Outstanding loans
- Income replacement requirements
- Critical financial responsibilities
- Coverage gaps
The amount of cover should relate to actual responsibilities, not simply a number suggested by a salesperson. Employer health insurance, for example, can be useful, but relying entirely on it may create a problem if you change jobs. Likewise, buying several policies does not automatically mean you are adequately protected. The better approach is to identify the financial risk first and then select suitable protection.
Investments Should Follow the Job Each Goal HasOnce goals, cash flow and protection are clear, investments can be selected with greater confidence. This is where many people start too early. They see a promising mutual fund, stock, fixed deposit or new investment opportunity and then try to find a goal for it. A financial plan works in the opposite direction. First identify the purpose and time horizon. Then consider the level of risk that is appropriate for that goal. For example:
- Near-term requirements generally need greater stability and liquidity
- Long-term wealth creation may allow greater exposure to growth-oriented assets
- Retirement planning requires a combination of accumulation and future income planning
- Large goals should not depend entirely on one investment category
- Regular investments can help build discipline over long periods
- Asset allocation should reflect both risk capacity and risk tolerance
Diversification also matters. Holding ten different mutual funds does not necessarily create meaningful diversification if they all invest in similar companies or sectors. The goal is not to collect investments. The goal is to build a portfolio that has a clear reason for existing.
Tax Planning Changes the Amount You Actually KeepA financial plan should also consider taxes because investment returns are meaningful only after accounting for taxation. Tax planning does not mean buying products purely to save tax. It means arranging legitimate financial decisions efficiently while keeping your actual goals in focus. For an individual in India, tax considerations can arise from salary, business income, capital gains, interest income, rental income and other sources. A useful plan reviews:
- Applicable income tax regime
- Available deductions and exemptions
- Tax treatment of investments
- Capital gains implications
- Tax impact of selling investments
- Home loan-related considerations where applicable
- Retirement-oriented investments
- Timing of certain financial transactions
Tax rules can also change, so a strategy that worked a few years ago may not remain optimal forever. The right sequence is important. First decide what you need financially. Then consider how taxation affects that decision. Tax saving should support the plan, not become the reason for making an unsuitable investment.
Retirement Planning Needs More Than a Target NumberRetirement is one of the few goals where the timeline is long and the final cost is difficult to estimate. A retirement plan should not simply say, "I need ₹2 crore." The calculation needs to consider current spending, expected inflation, retirement age, life expectancy, existing assets, future contributions and the lifestyle you want after retirement. It is also useful to think about expenses in two groups. Essential expenses may include housing, food, healthcare and utilities. Lifestyle expenses may include travel, hobbies, dining out and other discretionary choices. This distinction helps create a more realistic retirement estimate. Healthcare deserves particular attention because medical expenses can become a significant part of later-life spending. A good retirement strategy also considers what happens after accumulation. Building a large corpus is only one part of the problem. You also need a sensible withdrawal strategy that balances income needs with the longevity of your savings. Starting early helps because time gives investments a longer period to compound. However, starting late does not mean planning is pointless. It simply means the required savings rate and investment discipline may need to be stronger.
Debt Management Can Change the Entire Financial PlanDebt is often treated separately from investments, but the two are closely connected. A high-interest loan can quietly reduce the benefit of otherwise good investment decisions. Paying down expensive debt may sometimes provide greater financial improvement than adding another investment. This does not mean every loan should be closed immediately. Home loans, education loans and other borrowing arrangements need to be evaluated according to their cost, tax treatment, liquidity requirements and overall financial position. A debt review should look at:
- Outstanding principal
- Interest rate
- Remaining tenure
- EMI as a percentage of income
- Prepayment terms
- Floating versus fixed interest structure
- Other investment opportunities
- Emergency savings available after repayment
For instance, aggressively prepaying a loan while keeping no emergency reserve can leave a household financially vulnerable. The better decision depends on the complete picture. A financial plan should therefore balance debt reduction with liquidity, protection and long-term investing rather than treating any single objective as automatically superior.
Financial Plan Components Must Change When Life ChangesA financial plan is not something you prepare once and put away. Income changes. Families grow. Parents may need support. Children start school. Loans end. Careers change. Businesses expand. Tax rules move. Investment values fluctuate. These events can alter the original assumptions behind your plan. A useful review should happen when there is a significant change, such as:
- Marriage or the birth of a child
- A major salary increase or decrease
- Job change or business transition
- Purchase or sale of property
- Significant new loan
- Change in dependants
- Major inheritance
- Retirement approaching
- Changes in insurance coverage
- A major shift in financial goals
An annual review is also useful even when nothing dramatic happens. The purpose is not to constantly change investments. In fact, excessive changes can create unnecessary costs and confusion. Instead, review whether your goals, savings rate, risk level, insurance and asset allocation still make sense. The best financial plan is not the one that never changes. It is the one that changes when your life genuinely requires it.
A Good Financial Plan Should Tell You What to Do NextThe final test of a financial plan is simple: can you use it? A document filled with percentages, projections and product names is not necessarily a useful plan. You should be able to look at it and understand what needs to happen next month, next year and over the next decade. A practical action plan may include:
- Build or strengthen the emergency reserve
- Clear expensive debt
- Review life and health insurance
- Define specific financial goals
- Set monthly investment amounts
- Allocate investments according to time horizons
- Review tax planning before the relevant deadlines
- Track progress against each goal
- Review the plan at least annually
- Update the strategy after major life changes
This is where the different financial plan components come together. Your income funds the strategy. Your budget creates the surplus. Your emergency savings provide stability. Insurance protects against major risks. Investments work towards goals. Tax planning improves efficiency. Reviews keep the entire system aligned. That connection is what turns financial planning from a collection of financial products into a genuine decision-making framework.
Conclusion: Financial Planning Is a System, Not a Product ListA useful financial plan brings several moving parts together: cash flow, goals, emergency savings, insurance, debt, investments, taxes, and retirement preparation. The real strength lies in how these pieces support one another. Good financial plan components should make your financial decisions clearer, not more complicated. Start with where you are, define where you want to go, and then decide how each rupee should contribute to that journey. For practical investment and financial planning insights, exploreMunafaWaala and make your next financial decision with greater clarity.
Best Age Calculator Calculate Exact Age Online Without Manual Math
Best Age Calculator Calculate Exact Age Online Without Manual Math
Why FC27 Midfield Roles Matter in the U4gm 4-1-4-1
The best meta 4-1-4-1 custom tactics in FC27 should give your striker support without leav...
Symptoms of Pregnancy After Embryo Transfer in IVF
Symptoms of Pregnancy After Embryo Transfer in IVF The IVF journey can bring many emoti...
