Quick Answer: What Determines the Cost of Yacht Insurance?
- Yacht insurance costs are primarily influenced by the vessel's insured value, size, type, age, condition, and intended navigation area.
- An owner's boating experience, captain qualifications, previous claims, and crew training can affect how insurers assess operational risk.
- Coverage limits, deductibles, liability protection, and optional equipment coverage determine the level of financial protection and the overall policy cost.
- Safety systems, professional maintenance, and documented risk-management practices may help improve insurability or qualify an owner for certain discounts, depending on the insurer.
Owning a yacht involves more than the purchase price, marina fees, fuel, and routine maintenance. Insurance is another important part of the annual operating budget, particularly for owners who cruise along exposed coastlines, travel between countries, or operate larger motor yachts with expensive onboard systems. Understanding what influences yacht insurance premiums can help owners compare policies and avoid paying for protection that does not match their actual boating needs.
Insurance providers assess several aspects of a vessel and its operation before offering coverage. A 40-foot motor yacht used for occasional coastal trips presents a different risk profile from a similarly valued sailing yacht used for extended offshore passages. Even two boats of the same model and age may receive different quotations because their maintenance records, ownership history, navigation limits, and equipment differ.
For yacht buyers, these considerations are worth reviewing before completing a purchase. Insurance availability and policy conditions can influence the total cost of ownership, especially when a vessel requires a professional survey or additional safety improvements. The following factors explain how insurers typically evaluate yacht-related risks and what owners can review when seeking suitable coverage.
1. Yacht Value, Size, and Type
The vessel itself is one of the main starting points in an insurance assessment. Its replacement cost, construction, dimensions, propulsion system, and onboard equipment all influence the potential financial exposure faced by an insurer.
How Yacht Purchase Price and Insured Value Affect Premiums
A yacht's insured value is closely connected to the potential cost of repairing or replacing it after a covered loss. Higher-value vessels generally involve greater financial exposure, particularly when they feature custom interiors, advanced navigation electronics, specialist propulsion systems, or expensive tenders.
However, the purchase price and insured value are not always identical. Depending on the policy, coverage may be based on an agreed value or another valuation method. Owners should clarify how depreciation, partial damage, total loss, and equipment replacement are handled rather than comparing quotations solely by the annual price.
Differences in Insurance Costs Between Motor Yachts, Sailing Yachts, and Catamarans
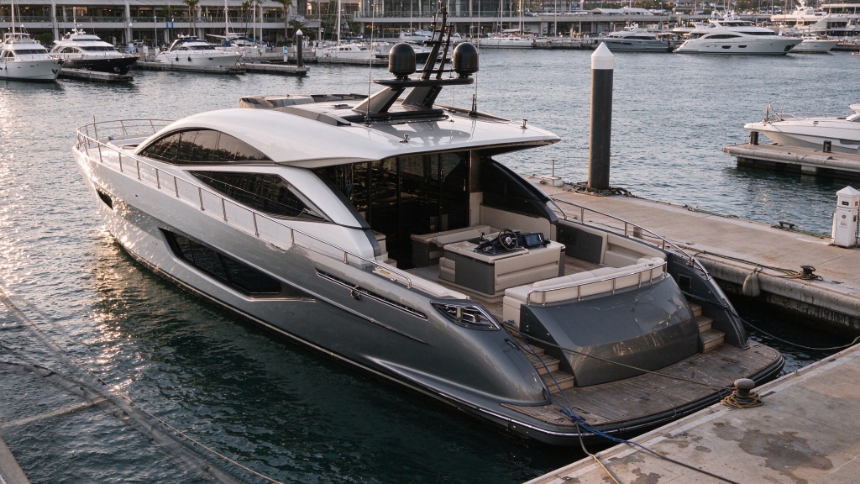
Different yacht types create different underwriting considerations. Motor yachts may have higher-value engines, fuel systems, and mechanical components, while sailing yachts involve rigging, sails, masts, and other equipment that can be costly to repair. Insurers consider these systems alongside the vessel's value and intended use.
Catamarans also have distinct characteristics. Their twin-hull construction and wider beam can provide additional living space and stability at anchor, but their dimensions, specialized structural components, and repair requirements may affect risk assessments. The final quotation depends on the specific design, construction, operating area, and insurer's underwriting criteria rather than the vessel category alone.
How Yacht Length, Design, and Onboard Equipment Influence Insurance Rates
Length is another factor because larger yachts can involve higher repair costs, more complex systems, and greater potential liability. A larger vessel may also require qualified crew or a captain with specific experience, depending on its size and operating conditions.
Design and equipment matter as well. Advanced radar, autopilot systems, stabilizers, generators, hydraulic equipment, and custom navigation installations can increase the value of the insured vessel. Owners should provide accurate equipment inventories and disclose significant modifications so the policy reflects the yacht's actual configuration.
2. Yacht Age, Condition, and Maintenance History
A yacht's age provides useful information, but it does not tell the whole story. Insurers also look at structural condition, mechanical reliability, maintenance standards, and evidence that potential problems have been addressed.
Why Yacht Age Matters When Calculating Insurance Premiums
Older yachts may present a greater likelihood of corrosion, material fatigue, outdated electrical systems, or mechanical failure. As a vessel ages, replacement parts can also become harder to source, potentially increasing repair time and costs after an incident.
Nevertheless, an older yacht is not automatically a poor insurance risk. A well-maintained vessel with documented refits and regular inspections may be viewed more favorably than a newer boat with neglected maintenance or unresolved defects. The quality of upkeep often provides important context beyond the launch year.
How Hull Condition, Engine Performance, and Mechanical Reliability Affect Coverage
The hull is a major consideration because structural damage, osmosis, delamination, and previous grounding incidents can affect seaworthiness. During a haul-out inspection, surveyors may examine the hull surface, underwater fittings, propellers, rudders, and keel attachments for visible defects or signs of deterioration.
Engine and mechanical condition are equally important, especially on motor yachts that depend on propulsion systems for routine operation. Evidence of overheating, oil leaks, corrosion, poor servicing, or recurring mechanical faults may lead to further inspection or specific policy conditions. Owners should resolve significant defects before assuming that a standard policy will cover every resulting loss.
The Importance of Maintenance Records and Professional Marine Surveys
Maintenance records help demonstrate that a yacht has received appropriate care. Useful documents include engine servicing invoices, rigging inspections, antifouling records, repair receipts, equipment replacement details, and records of previous structural work.
A professional marine survey can provide an independent assessment of the vessel's condition and identify issues that may not be obvious during a viewing. Some insurers require a recent survey for older or higher-value yachts, while others may request one when the vessel has undergone major repairs or modifications. Owners should confirm survey requirements with the insurer before arranging an inspection.
3. Navigation Area and Intended Yacht Usage
Where and how a yacht is operated can change its risk profile considerably. A vessel kept in a sheltered marina and used for occasional day trips faces different exposure from one regularly crossing open water or operating in regions affected by tropical storms.
Coastal Cruising vs. Offshore and Ocean Navigation
Coastal cruising generally takes place closer to ports, marinas, and available assistance. Offshore and ocean navigation can involve longer periods away from repair facilities, more demanding weather conditions, and greater difficulty obtaining emergency support.
Insurers may therefore apply different navigation limits, deductibles, or policy conditions according to the intended cruising area. Owners planning longer passages should confirm that their policy covers the complete route, including seasonal restrictions, approved regions, and any requirements for crew qualifications or passage planning.
How Geographic Location and Severe Weather Risks Affect Premiums
The yacht's home port and cruising region can influence insurance costs. Areas exposed to hurricanes, typhoons, severe storms, high theft rates, or challenging navigational conditions may present additional risks. In some regions, insurers may impose seasonal navigation restrictions or require vessels to follow specific storm-preparation procedures.
For owners in the Mediterranean, Caribbean, or western Pacific, the relevant exposure can vary significantly by season and location. A policy that covers normal marina use may not automatically provide the same protection during a planned passage through a high-risk weather region.
Differences Between Private Yacht Use and Commercial Charter Operations
Private recreational use and commercial charter activity are generally treated differently by insurers. A privately operated yacht may carry family members and invited guests, whereas a charter vessel transports paying passengers and may operate on a more frequent schedule.
Commercial activity can introduce additional passenger liability, crew employment, operational, and regulatory considerations. Owners who intend to offer bareboat or crewed charters should disclose this use before purchasing coverage. A standard private-use policy may not provide the protection required for commercial operations, even if the vessel itself is otherwise suitable.
4. Owner Experience and Yacht Operating History
The person responsible for operating a yacht is another important part of the underwriting assessment. Insurers may consider the owner's boating background, qualifications, previous incidents, and the experience of anyone regularly handling the vessel.
How Boating Experience and Captain Qualifications Influence Insurance Rates
An owner with several years of relevant boating experience may present a different risk profile from someone purchasing their first yacht. Insurers may ask about previous vessel ownership, time spent at sea, experience with similar yacht types, and familiarity with the intended navigation area.
For larger motor yachts and offshore vessels, captain qualifications can be particularly important. Depending on the yacht and jurisdiction, insurers may require a professionally qualified captain or evidence of relevant training. Owners should provide accurate information about who will operate the vessel rather than assuming that personal experience alone will satisfy every policy requirement.
The Impact of Previous Accidents and Insurance Claims
Previous groundings, collisions, fires, thefts, and machinery-related incidents can influence underwriting decisions. Insurers may review claim frequency, the severity of previous losses, and whether the underlying causes have been addressed.
A previous claim does not necessarily prevent an owner from obtaining coverage. However, repeated incidents or unresolved safety issues may result in higher quotations, additional deductibles, restricted coverage, or requests for further documentation. When requesting insurance, owners should disclose relevant incidents accurately and provide evidence of completed repairs.
Why Crew Experience and Safety Training Matter to Insurers
A yacht's crew can influence how effectively the vessel is operated and how quickly an emergency is managed. Experienced crew members may be more familiar with navigation procedures, engine-room checks, fire response, and onboard safety equipment.
Training records can also help demonstrate a structured approach to risk management. Depending on the insurer, relevant qualifications may include recognized boating certificates, navigation training, first aid, and emergency-response courses. For yachts regularly operated by multiple crew members, clear responsibilities and consistent safety procedures are particularly valuable.
5. Coverage Options, Deductibles, and Policy Limits
The selected policy structure has a direct effect on the amount an owner pays and the financial protection available after an incident. Comparing insurance quotations requires looking beyond the annual cost to understand exactly what is included, excluded, and subject to additional conditions.
Understanding Hull and Machinery Insurance and Liability Coverage
Hull and machinery coverage generally protects the insured yacht against specified physical losses or damage, subject to the policy wording. Depending on the policy, covered components may include the hull, engines, propulsion equipment, and permanently installed systems.
Liability coverage addresses certain legal responsibilities arising from yacht operation, such as covered third-party bodily injury or property damage. Owners should also review whether the policy includes wreck removal, pollution liability, or protection for passengers and crew. These provisions can be especially relevant when operating a larger yacht or entering busy marinas.
How Deductibles and Coverage Limits Affect Annual Premiums
A deductible is the amount the owner must pay toward a covered claim before the insurer contributes. Selecting a higher deductible may reduce the annual insurance cost, but it also means accepting more financial responsibility when damage occurs.
Coverage limits determine the maximum amount available for specified claims or categories of loss. Owners should consider whether the limits are appropriate for the yacht's value, potential third-party exposure, and intended navigation area. Some policies also apply separate deductibles for named storms, grounding, or other specific risks, so these details deserve close attention.
Additional Protection for Personal Belongings and Onboard Equipment
Standard yacht coverage may not automatically protect every item carried aboard. Personal belongings, fishing equipment, portable electronics, water sports equipment, tenders, and specialist navigation devices may require separate limits or optional extensions.
Owners should prepare an inventory of valuable items and check how the policy treats permanently installed equipment compared with removable property. It is also important to understand exclusions, geographical restrictions, and whether replacement is based on current value or new-for-old terms. Accurate documentation can make a difference when a claim needs to be assessed.
6. Safety Equipment, Risk Management, and Insurance Discounts
Safety equipment does more than support compliance with boating regulations. It can help prevent incidents, improve emergency response, and demonstrate that the owner takes vessel operation seriously. Some insurers may recognize these measures when evaluating risk or offering discounts, although savings are never guaranteed.
How Navigation Electronics and Emergency Equipment Reduce Operational Risks
Modern navigation systems can help crews monitor their position, identify nearby vessels, and plan safer routes. Chartplotters, radar, AIS, GPS, depth sounders, and reliable communication equipment can support better decision-making, particularly when visibility deteriorates or traffic becomes busy.
Emergency equipment is equally important. Life rafts, life jackets, EPIRBs, fire extinguishers, and suitable first-aid supplies can improve preparedness when an incident occurs. Owners should check equipment expiry dates, service intervals, and accessibility rather than focusing only on the number of items carried aboard.
The Role of Fire Protection, GPS Tracking, and Anti-Theft Systems
Fire is a significant concern on yachts because engines, fuel systems, batteries, generators, and electrical installations can create potential ignition sources. Suitable fire detection systems, engine-room suppression equipment, and regularly inspected extinguishers can strengthen onboard protection.
GPS tracking and anti-theft systems may also help reduce certain security risks. Alarms, secure access points, remote monitoring, and vessel tracking can support theft prevention and recovery efforts. Whether these installations affect the insurance quotation depends on the insurer, the equipment specification, and whether the systems meet its requirements.
Safety Certifications and Preventive Maintenance as Potential Cost-Saving Factors
Some insurers may offer favorable terms to owners who demonstrate consistent maintenance and recognized safety training. Relevant evidence can include professional survey reports, engine service records, rigging inspections, safety equipment certifications, and documented crew training.
Preventive maintenance can also reduce the likelihood of avoidable breakdowns and damage. Regularly inspecting hoses, electrical connections, through-hull fittings, steering systems, and bilge pumps helps identify problems before they develop into more serious incidents. Owners should ask insurers which specific measures qualify for discounts rather than assuming that every upgrade will reduce the annual cost.
Conclusion
Yacht insurance costs are influenced by several connected factors, including vessel value, size, design, age, condition, navigation area, and intended use. Owner experience, previous claims, crew qualifications, coverage limits, and deductibles also shape how insurers assess the overall risk.
For yacht owners, the most practical approach is to prepare accurate vessel information, maintain complete service records, and compare policy wording rather than focusing exclusively on the cheapest quotation. A recent marine survey and suitable safety equipment may also help demonstrate responsible ownership.
Before purchasing or renewing a policy, discuss navigation plans, commercial activities, and major equipment with the insurer. A policy that reflects the yacht's real operating conditions is more valuable than one that appears inexpensive but leaves important risks uninsured.
FAQ
Q1: What is the biggest factor affecting yacht insurance premiums?
A1: The yacht's insured value is a major factor because it influences potential claim costs. Vessel condition, navigation area, intended use, and owner experience also affect the insurer's assessment.
Q2: Does the age of a yacht affect insurance costs?
A2: Yes. Older yachts may have greater maintenance and mechanical risks, but documented servicing, professional surveys, and completed repairs can help demonstrate good condition.
Q3: Can installing additional safety equipment reduce yacht insurance premiums?
A3: Potentially. Some insurers offer discounts for approved alarms, tracking systems, fire protection, or safety equipment, but eligibility and savings depend on individual underwriting requirements.