Hidden costs of emergency loans in the UK: APRs, fees & risks you must understand
Emergency loans are expensive. They charge very high interest rates because of some hidden fees. You should analyse your repayment capacity to get the loans.
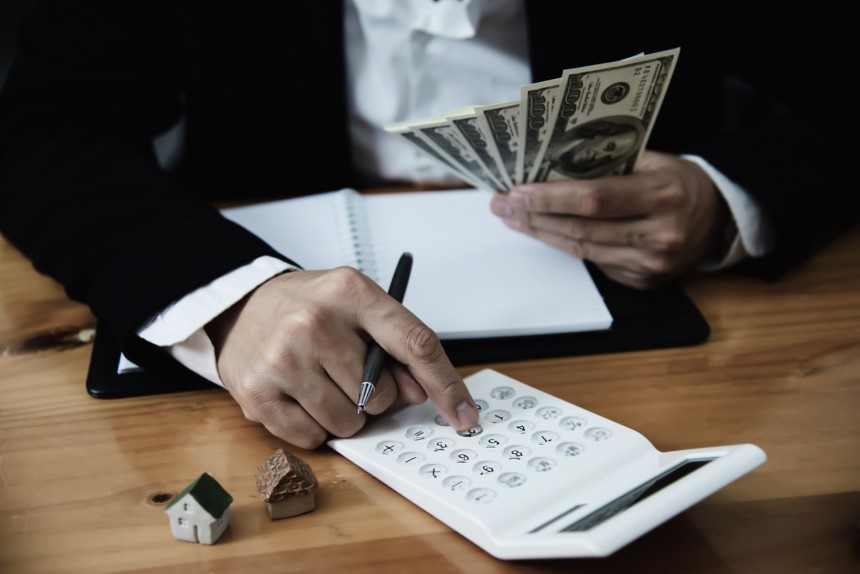
Emergency loans are short-term loans that are generally aimed at subprime borrowers to help them tide them over during financial emergencies. Unexpected expenses can occur at any time. It is likely that your savings are not enough to meet the unforeseen. In order to bridge the gap in cash, emergency loans have been designed.
What are the key features of emergency loans?
As you know, these loans are short-term loans aimed at subprime borrowers to help them tide them over during financial emergencies; these loans come with a very small amount of money. Under no circumstances could the size of these loans be more than £1,000.
Mainly, lenders restrict the lending amount. Since the whole amount is to be paid back in one fell swoop, the repayment term of these loans cannot be more than a month. In some cases, the entire debt is to be paid down within a period of 14 days.
You can use emergency loans for a wide range of activities, such as:
- Your car has broken down.
- There is a leaky roof.
- You have been facing some plumbing issues.
- You have a medical emergency that is not covered by medical insurance.
Getting approval for emergency cash immediately in the UK is not challenging at all. You just have to fill in a loan application to provide all income and expenditure details. Your lender will review your application and your credit report. Once your application is approved, money will be transferred to your bank account.
It is worth bearing in mind that not all lenders run hard inquiries to approve emergency loans. They run soft inquiries that do not appear on your credit file, and hence you do not lose your credit points. Beware of those lenders who run neither a hard check nor a soft check. Such lenders could be loan sharks.
No authorised lender is permitted to sign off on a loan application without a credit check. Loan sharks charge exorbitant interest rates. They tend to make profits by exploiting you. These loans are so expensive that you will not be able to discharge your debt, and eventually, you will find yourself in an abyss of debt.
Emergency loans are expensive because of hidden fees
Interest rates for emergency loans are undoubtedly expensive. One of the reasons why these loans are expensive is that they are aimed at subprime borrowers. The risk of default is too high. Even if you manage to get these loans at lower interest rates, they will not be inexpensive or affordable.
Interest rates for these loans are quite high; however, the FCA has capped interest rates up to 0.8% per day, which means no lender can charge more than 0.8% per day. Unfortunately, in addition to interest, you are to pay additional charges and fees. Here comes the role of the APR. It refers to the annual percentage rate. This involves interest rates as well as additional charges.
While interest rates are capped at 292% if the loan is accrued for a full one year, the APR could go up to 1500%. If you miss the payment, late payment fees will be charged, which are capped at £15. Unfortunately, in addition to late payment fees, interest penalties are also charged. This is why the APR goes up to 1500%.
The FCA has clearly recommended that no borrower is supposed to pay back more than 100% of the amount in interest payments. The 1500% APR means that if you borrow £100, for instance, for the full one year, you will end up paying 1500 as accrued interest. This is why the cost of such short-term high-cost debt accumulates so quickly. While you are recommended to make a decision based on interest rates, you should carefully evaluate the APR.
In addition to late payment fees and interest, lenders charge hidden costs. You will most likely be aware of hidden fees at the time of signing a loan agreement. Make sure that you carefully read the fine print.
- Processing fees
Processing fees are also known as loan origination fees. Most of the lenders charge processing fees at the time of signing off on your loan. The details about processing fees can be found in a loan agreement. Lenders bifurcate the cost in a loan agreement. At the time of signing it, you should read it, so you know exactly what you are paying.
- Early repayment fees
If you repay your debt before the due date, some lenders will charge early repayment fees. A golden rule of thumb says that you should ask your lender about it in advance. Not all lenders charge early repayment fees.
Sometimes, it is almost equivalent to the amount of accrued interest that you were supposed to pay back otherwise. Lenders charge early repayment fees in order to mitigate the loss in the form of interest. You can get to know about early repayment charges in a loan agreement.
Risks pertaining to emergency loans
Here are the risks associated with emergency loans:
The most significant risk related to emergency loans is that there is a high risk of falling into debt. Interest rates are too high. If you fail to repay the debt on time, you will end up rolling it over. Eventually, you will fall into an abyss of debt.
These loans cannot help improve your credit score, but they will certainly take a toll on your credit rating if you fail to meet your obligations.
There is a high risk of getting stuck with unauthorised lenders. Some unregistered lenders also provide these loans. You might end up with these lenders if you have been rejected elsewhere. Borrowing from unregistered lenders is not recommended, as they can trap you in an ongoing cycle of debt.
The final word
Emergency loans are short-term, high-cost loans. At the time of using these loans, you should carefully check the APR and interest rates. Carefully analyse the pros and cons of these loans and then decide whether you should use them or not.
What Factors Should You Consider Before Choosing Female Viagra Pills?
Before choosing a product, identify the concern you want to address. Low sexual desire, di...

Top High-Puff Disposables Ranked - Why Maskking IceX Leads the Cooling...
Discover Inspiring Music Education for Children and Adults in Singapor...