Conventional Home Loans in Texas: A Complete Guide for Homebuyers
Learn about Conventional Home Loans in Texas, including eligibility, benefits, and financing options. Get expert mortgage guidance from Fahey Mortgage.
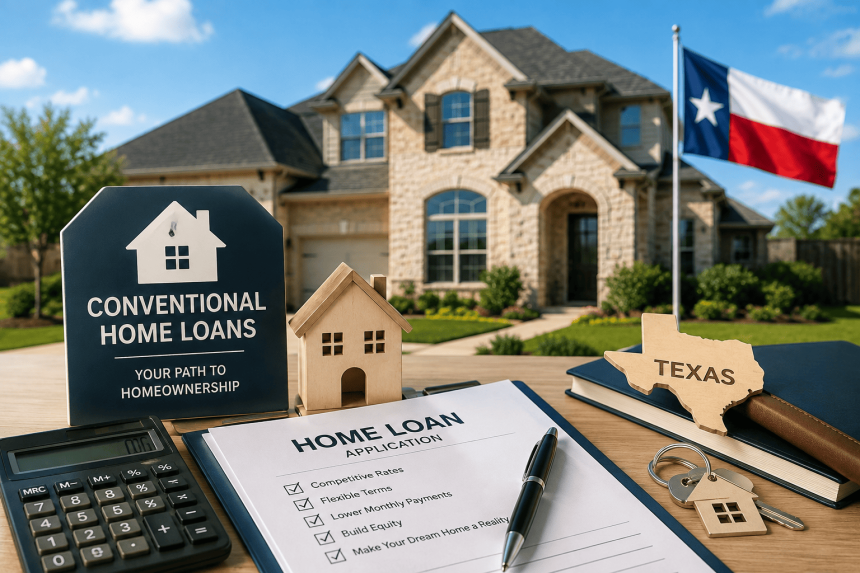
Buying a home is one of the biggest financial decisions you'll ever make, and choosing the right mortgage can have a lasting impact on your budget and future. If you're considering Conventional Home Loans in Texas, you're looking at one of the most popular financing options for homebuyers across the state. These loans offer competitive interest rates, flexible loan terms, and fewer long-term costs for qualified borrowers. Whether you're purchasing your first home, upgrading to a larger property, or investing in your future, understanding how conventional loans work can help you make a confident decision.
Conventional home loans are mortgages that are not insured or guaranteed by a government agency. Instead, they follow lending guidelines established by Fannie Mae and Freddie Mac. Because these loans are designed for borrowers with stable finances and good credit, they often provide attractive interest rates and flexible repayment options.
Many Texas homebuyers prefer conventional financing because it offers greater flexibility and can reduce long-term borrowing costs compared to some government-backed loan programs.
Some of the key features include:
- Competitive fixed and adjustable interest rates.
- Flexible loan terms.
- Available for primary homes, second homes, and investment properties.
- Various down payment options.
- Opportunity to remove private mortgage insurance (PMI) once eligible.
These advantages make conventional financing a popular choice throughout Texas.
Choosing Conventional Home Loans in Texas gives qualified buyers access to flexible financing that works well for many different financial situations.
Texas continues to attract homeowners because of its strong economy, growing job market, affordable housing in many regions, and diverse communities. Whether you're purchasing a home in Dallas, Houston, Austin, San Antonio, or a smaller city, conventional loans provide financing options that fit a wide range of budgets.
Some reasons buyers choose conventional loans include:
- Lower overall borrowing costs.
- Flexible property options.
- Competitive mortgage rates.
- Fewer restrictions compared to some government-backed loans.
- Opportunity to avoid long-term mortgage insurance costs.
For borrowers with solid financial profiles, conventional loans often provide significant long-term savings.
Although qualification requirements vary by lender, conventional loans generally require borrowers to demonstrate financial stability and the ability to repay the loan.
Most lenders evaluate:
- Credit score.
- Stable employment history.
- Reliable monthly income.
- Debt-to-income ratio.
- Available savings for down payment and closing costs.
A stronger financial profile may improve your chances of securing better interest rates and more favorable loan terms.
Many buyers compare conventional financing with FHA and VA loans before choosing the right mortgage. Conventional loans offer several unique benefits for qualified borrowers.
Some of the biggest advantages include:
- Competitive interest rates.
- Flexible loan amounts.
- Multiple repayment term options.
- Lower overall loan costs for qualified borrowers.
- Ability to cancel private mortgage insurance after meeting equity requirements.
- Financing available for different property types.
- Fewer property condition restrictions than some government-backed loans.
These benefits make conventional mortgages one of the most versatile financing solutions available.
One common misconception is that conventional loans always require a large down payment. In reality, down payment requirements vary depending on the lender, borrower qualifications, and loan program.
Qualified borrowers may have several financing options available, allowing them to purchase a home while balancing monthly payments and upfront costs. Making a larger down payment can reduce monthly mortgage expenses, but many buyers qualify with much less than they expect.
Discussing your financial goals with a mortgage professional can help determine the best option for your situation.
Your credit profile plays an important role when applying for Conventional Home Loans in Texas. Generally, borrowers with higher credit scores receive better interest rates and loan terms.
Lenders often review:
- Credit history.
- Payment consistency.
- Income stability.
- Existing monthly debt.
- Cash reserves.
Improving these areas before applying may increase your approval chances while lowering your long-term borrowing costs.
Understanding each stage of the mortgage process helps buyers prepare and avoid unnecessary delays.
The typical application process includes:
- Review your financial readiness.
- Gather income and financial documents.
- Apply for mortgage pre-approval.
- Determine your home buying budget.
- Shop for your ideal property.
- Complete the home appraisal.
- Final underwriting review.
- Close on your new home.
Preparing documents in advance can make the approval process smoother and faster.
Many mortgage applications experience delays because borrowers make financial changes before closing. Avoiding these mistakes can help keep your loan on track.
Try not to:
- Open new credit accounts.
- Finance large purchases.
- Change jobs unexpectedly.
- Miss monthly payments.
- Spend your savings before closing.
- Deposit undocumented funds into your account.
Maintaining financial stability throughout the mortgage process gives lenders greater confidence in your application.
A conventional mortgage may be an excellent choice if you have steady income, a solid credit history, and want flexible financing with fewer long-term costs. It works well for first-time buyers, repeat homeowners, and even investors purchasing eligible properties.
Before selecting a loan, compare available mortgage options, monthly payment estimates, interest rates, and your long-term financial goals. An experienced lender can help you determine whether conventional financing is the best fit for your situation.
Finding the right lender can make the home-buying experience much easier. Experienced mortgage professionals can explain your financing options, answer your questions, and guide you from pre-approval through closing.
If you're considering Conventional Home Loans in Texas, Fahey Mortgage is dedicated to helping homebuyers secure financing that fits their unique financial goals. Their knowledgeable team offers personalized guidance, competitive loan solutions, and exceptional customer service throughout every stage of the mortgage process.
A Conventional Home Loans in Texas program can provide affordable financing, flexible loan options, and long-term financial benefits for qualified buyers. Whether you're purchasing your first home or moving into your next property, choosing the right mortgage is an important step toward achieving your homeownership goals.
If you're ready to buy a home in Texas, now is the perfect time to get pre-approved and explore your financing options. Contact a trusted mortgage professional today and take the first step toward owning the home you've been dreaming about.
A conventional home loan is a mortgage that is not insured by a government agency and follows lending guidelines established by Fannie Mae and Freddie Mac.
Qualification depends on factors such as credit score, income, employment history, debt-to-income ratio, and available funds for closing.
Yes. Conventional loans are available to both first-time and repeat homebuyers who meet lender qualification requirements.
Some borrowers may be required to pay PMI depending on their down payment. In many cases, PMI can be removed once sufficient home equity is reached.
Most conventional home loans close within approximately 30 to 45 days, although timelines vary depending on the lender and borrower documentation.

Dish Network Installers Near Me: Expert Satellite Dish Setup in Sharja...